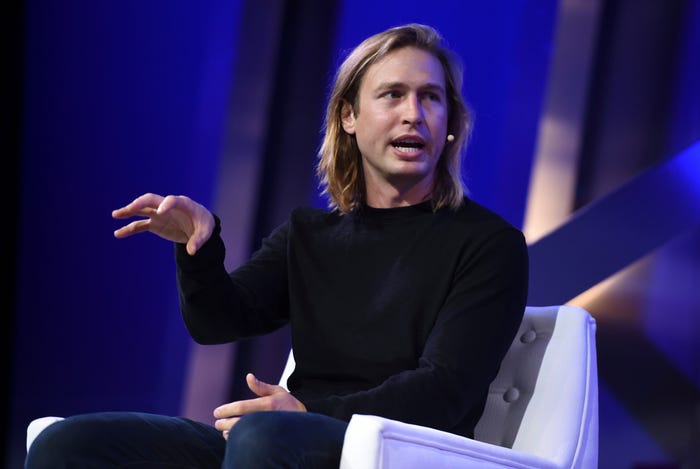
The future of finance, according to Plaid CEO Zach Perret, isn’t just digital – it’s autonomously intelligent.
Speaking at Semafor’s World Economic Summit in Washington, DC, Perret laid out a vision so bold it might make even the most tech-savvy among us pause.
He envisions a world where artificial intelligence doesn’t just assist with our money, but actively manages it.
This AI would make investment decisions, route paychecks, and handle every financial minutia without human intervention.
For Perret, this isn’t a distant fantasy; it’s an “inevitable” reality he personally yearns for.
“I want my financial life to be fully automated,” Perret declared.
He expressed a desire to never again have to think about the intricacies of personal finance.
This isn’t merely a Silicon Valley executive’s musing on convenience; it’s a profound statement about the evolving relationship between humans and their most sensitive data.
In Perret’s ideal scenario, a chatbot like ChatGPT wouldn’t just answer queries about your balance.
It would be your proactive, omniscient financial advisor, moving funds, optimizing portfolios, and ensuring every dollar is working its hardest.
All of this would happen while you remain blissfully unaware of the underlying mechanics.
The conviction behind Perret’s statements stems, in part, from the very nature of his company, Plaid.
As a fintech giant, Plaid serves as the invisible connective tissue between bank accounts and a myriad of digital finance apps, from Venmo to budgeting tools.
This position grants Perret a unique vantage point into the seamless flow of financial data and the increasing comfort users have with entrusting their monetary lives to technology.
For him, the leap from connecting apps to allowing AI to orchestrate these connections autonomously is a logical, even natural, progression.
Yet, this vision, while appealing in its promise of unparalleled efficiency and liberation from financial anxieties, naturally raises a host of questions.
Trust, for one, stands paramount.
Giving an AI “all the trust in the world” to manage one’s money implies an almost blind faith in algorithms.
It’s a belief that these systems are infallible, secure, and always acting in one’s best interest.
Perret, ever the early adopter, admits his high tolerance for risk.
“I’m super pro, like try everything new, and I’m willing to accept some risk for that,” he stated.
But how many among us share that same adventurous spirit when it comes to our life savings?
The average individual, grappling with the complexities of inflation, market volatility, and the perennial fear of identity theft, might find the idea of an AI making investment decisions a bridge too far.
The human element of understanding nuances, ethical considerations, and even the emotional attachment to money is something algorithms, no matter how advanced, struggle to replicate.
While an AI could meticulously analyze market data, would it truly understand the personal significance of a down payment for a first home or the need for a safety net for a child’s education?
Perret acknowledges this divergence in comfort levels, recognizing that not everyone will be as eager to hand over the reins.
However, he frames the choice as a personal one, within an “inevitable” broader trend.
The recent announcements from OpenAI, integrating apps like OpenTable, Instacart, Target, and Zillow into ChatGPT, and Walmart’s move to add instant checkout experiences to the chatbot, lend credence to Perret’s assertion that AI is rapidly permeating every facet of our digital existence.
If AI can order your groceries and book your dinner, why not manage your investments?
The implications of such a shift are profound.
On one hand, it could democratize sophisticated financial management, making expert-level planning accessible to everyone, regardless of their financial literacy or net worth.
It could free up countless hours spent budgeting, tracking, and worrying about money, allowing individuals to focus on pursuits that bring them greater joy and fulfillment.
The promise is a world where financial stress becomes a relic of the past, replaced by algorithmic serenity.
On the other hand, it introduces new vectors of risk.
What happens when an AI makes a catastrophic error?
Who is accountable?
How do we ensure these systems are free from biases, particularly when making decisions that could significantly impact an individual’s financial well-being?
The very notion of “personal decision” regarding AI involvement in finance might become increasingly blurred as the systems become more integrated and, perhaps, more persuasive.
If AI truly drives our financial lives, will opting out be a viable option, or will it become a competitive disadvantage?
Perret’s vision forces us to confront not just the technological capabilities of AI, but also our societal readiness for a paradigm shift in how we interact with money.
It challenges us to consider what it means to be financially independent when an intelligent machine handles the heavy lifting, and whether the convenience outweighs the potential loss of control or understanding.
As AI continues its relentless march into our daily routines, the question isn’t just if it can manage our money, but how we want it to, and what kind of financial future we are truly building.
-
Frank DiBernardo handles LNGFRM's Foodie and Miscellaneous writing tasks. He's always getting ideas from users, so don't be afraid to send an email to the editor.